A wedding is an important financial goal, but estimating its future cost can be challenging. Venue charges, catering, jewellery, clothing, photography and other arrangements can become significantly more expensive over time. Planning only for today’s wedding budget may therefore leave a substantial funding gap when the actual event arrives.
A SIP for wedding can help bring structure to this long-term goal. Instead of simply deciding on a lump-sum amount, you can work backwards from the expected wedding cost and build a dedicated corpus through regular investments.
Start With the Major Wedding Expenses
The first step in SIP for wedding planning is to identify the expenses that are likely to account for a significant portion of the budget.
For example, a wedding budget might include:
- Venue and catering
- Gold and jewellery
- Clothing and accessories
- Photography and videography
- Travel and accommodation
- Décor and entertainment
- Invitations and other miscellaneous expenses
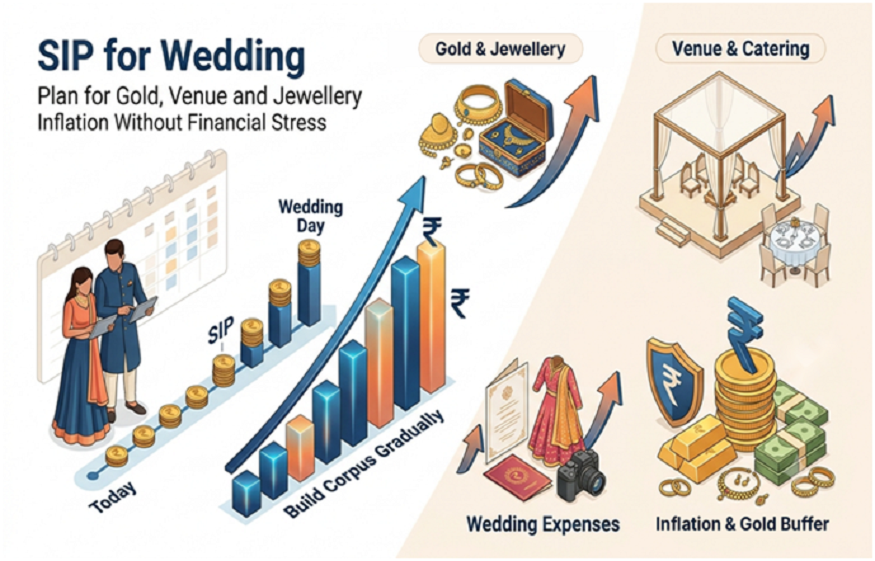
Among these, gold, jewellery and venue costs deserve particular attention because their prices can change considerably over time.
Read More : SME Loan Interest Rates: What Drives Them and How to Compare Offers
Account for Gold and Jewellery Inflation
Gold is often an important component of Indian weddings. However, estimating the future requirement simply by looking at today’s jewellery prices can be misleading.Suppose a family expects to spend ₹5 lakh on gold jewellery today but plans to purchase it five years from now. If gold prices rise over the period, the same jewellery requirement could cost substantially more.
Jewellery expenses can also include making charges, taxes and design-related costs, which means the final bill may not move exactly in line with the gold price.Instead of assuming that today’s ₹5 lakh requirement will remain ₹5 lakh, build a reasonable inflation assumption into your target and review it periodically.
Don’t Forget Venue Inflation
Venue and catering costs can also increase over several years. A wedding venue that costs ₹4 lakh today could command a considerably higher price when you are ready to book it.If your current wedding budget is ₹15 lakh and you expect to get married five years from now, applying an assumed annual inflation rate of 7% would put the projected cost at approximately ₹21 lakh.This is only an illustration. Actual wedding inflation can vary significantly depending on the city, venue category, season, guest count and type of celebration.
The purpose of inflation-adjusted planning is to prevent today’s budget from becoming tomorrow’s funding shortfall.
Convert the Goal Into a Monthly SIP
Once you estimate the future wedding corpus, you can determine how much needs to be invested every month. A sip calculator can help estimate the monthly SIP required based on your target corpus, investment period and assumed annualised return. Suppose your projected wedding requirement is ₹20 lakh after five years. If you assume an annualised investment return of 10% purely for illustration, a monthly SIP of approximately ₹25,800 could potentially accumulate close to ₹20 lakh over 60 months.
The return assumption is not guaranteed. Mutual fund investments are market-linked, and actual outcomes can differ. The calculation is more useful when treated as a planning framework rather than a promise of future returns.
Match Investments With Your Timeline
The investment strategy should reflect the time remaining before the wedding.If the wedding is several years away, an investor may have more flexibility to consider investments suited to a longer horizon, depending on risk tolerance. As the wedding approaches, protecting the accumulated corpus becomes increasingly important.
Money required in the near term should generally not be exposed unnecessarily to high market volatility. Gradually reviewing and adjusting the portfolio as the goal approaches can help reduce the risk of a significant market decline immediately before the wedding.
Review Your Wedding SIP Regularly
Wedding plans often evolve. The guest list may increase, the venue may change, or jewellery requirements may become different from the original estimate.Your sip for wedding planning should therefore not remain fixed for several years without review.For instance, if your salary increases, you could consider increasing the SIP through an annual step-up. Similarly, bonuses or other irregular income can be allocated toward the wedding corpus without relying entirely on monthly income.
A dedicated investment account or clearly identified goal-based portfolio can also make it easier to track progress.
Plan for the Wedding You Can Afford
The objective of a SIP for wedding is not simply to accumulate the largest possible amount. It is to create a realistic financial plan that accounts for rising costs while keeping the monthly commitment manageable.
Think of the goal in three layers:Gold & Jewellery + Venue & Celebration + Other Wedding Expenses
Estimate each category, factor in potential inflation, determine the future corpus and then work backwards to calculate the required monthly investment.Most importantly, avoid compromising your emergency fund, insurance protection or essential long-term financial goals just to increase the wedding budget. A well-planned wedding should ideally begin a new phase of life without creating an unnecessary financial burden.
Read More : How a Medical Office Staffing Agency Reduces Administrative Hiring Delays
Disclaimer: This article is for educational purposes only and should not be considered investment advice. Mutual fund investments are subject to market risks, and returns are not guaranteed. Inflation assumptions and investment illustrations are hypothetical and actual wedding costs and investment outcomes may differ.